The fee, the interest, the total — all of it before you give us your name. Start with what is actually spare each month, and we will tell you straight whether it fits.
Every rand of it, before you give us your name. The final figure comes from an affordability check and a person's decision.
Every fee below sits inside the maximums the National Credit Act allows. You will see the full total on your agreement — but you can see it here first, without giving us anything.
R 1 000 plus R 150 initiation, R 60 service fee and R 50 interest.
R 2 000 plus R 265 initiation, R 180 service fees and R 300 interest.
R 5 000 plus R 565 initiation, R 360 service fees and R 1 500 interest.
Every fee is inside the maximums the National Credit Act allows.
Nothing is decided yet. Someone reads every application, and we come back to you either way.
Credit is paid into your LynkPay account and repaid from it, so if you do not have one we open it with the same application. Keep your ID and a recent bank statement handy — we will ask for them next.
Step 1 of 3 · About you
We work out what you can afford from these, using the table the National Credit Act sets. Be straight with us — a bank statement will show the same figures.
We take your repayment from this account. Get it right — a wrong number means a failed payment and a fee nobody wants.
Photograph them or attach a file. We cannot decide without them, and sending them now means we do not have to phone you for them.
Your reference is
Someone will come back to you shortly.
Credit is paid into your LynkPay account and repaid from it. That is why the account is the starting point rather than an extra.
Your balance, your card, what you have spent and what it costs. No branch, no queue, no phoning to ask where you stand.
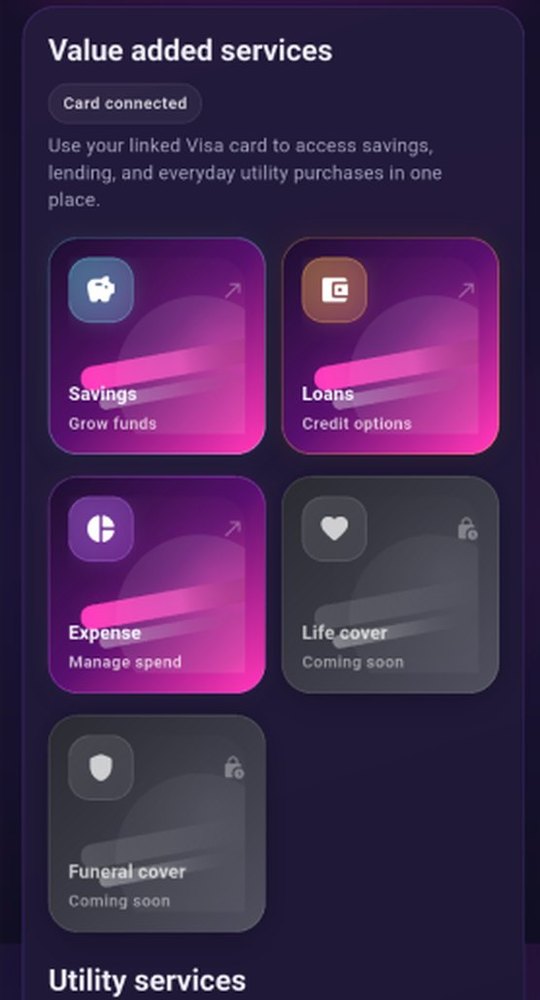
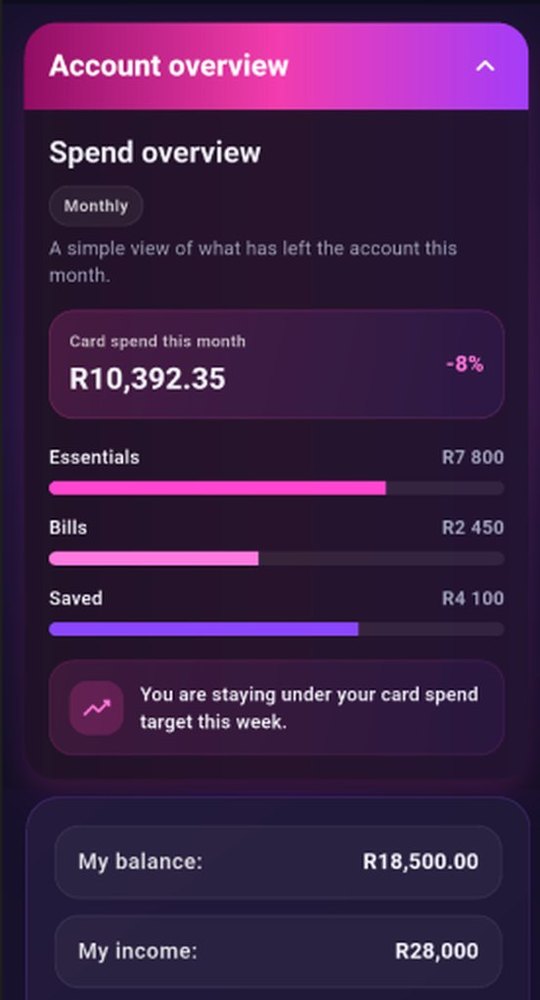
A LynkPay account is a place to keep your money, spend it, and see exactly where it went — whether or not you ever borrow anything.
This is the notice the application form points at.
If you apply, we use your name, ID number, contact details, income, expenses, employment and the documents you send to decide whether the loan fits. That is required by the National Credit Act. We cannot do it without your agreement — the first checkbox on the form.
The same agreement lets us ask a registered credit bureau (Datanamix) about your credit record. We send your ID number. We do not send the application until you have ticked that box, and we keep a record of the agreement — when, from which channel, and the exact words you saw. We do not run the enquiry without that record.
Only if you tick the second box. Agreeing to be assessed is not agreeing to receive marketing. You can leave it unticked and still apply.
We keep the application, the assessment and the consent record because the National Credit Act requires us to show how a decision was made. If you want a copy, or want marketing stopped, ask us using the details on this page.